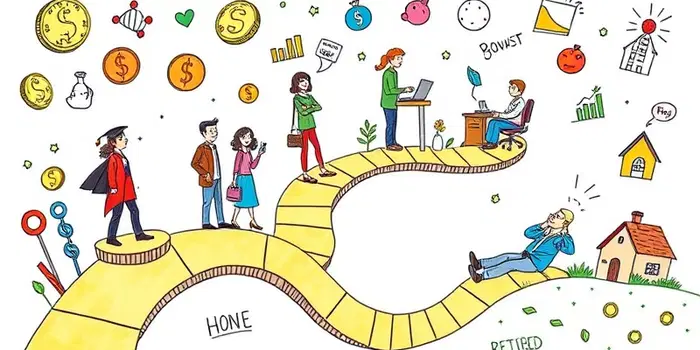
Investing is a journey that changes as our lives unfold. While market trends can guide us, the real key lies in matching our strategy to the right life stage. By understanding when you need funds, how much volatility you can endure and what goals you prioritize, you can build a flexible plan that adapts over time.
Why Investing Must Evolve Over Time
Our financial goals rarely stay static. A graduate entering the workforce faces different trade-offs than a parent saving for college or a couple nearing retirement. The concept of cash reserves and debt captures this dual focus. Building a foundation of liquidity and tackling high-interest liabilities are prerequisites to long-term growth. Without this groundwork, even the most diversified portfolio can falter if you’re forced to liquidate assets at a loss.
Building Your Financial Foundation
Before you allocate funds to stocks, bonds or real estate, begin with a clear spending plan. List income sources, essential expenses and discretionary spending. Only then decide how much to redirect toward savings, investments or debt reduction. Experts recommend an emergency reserve equal to three to six months of essential expenses, held in liquid vehicles like savings accounts or short-term CDs.
- Automate a monthly transfer to savings
- Target high-interest debt first
- Review and adjust your budget quarterly
- Maintain a minimum cash cushion
Paying down credit-card balances often yields a guaranteed return equal to the avoided interest, making it a powerful complement to market-based strategies. A balanced approach may involve contributing just enough to capture an employer retirement match while accelerating high-interest repayments.
Stage 1: Students and Young Adults
For the youngest investors, the greatest asset is time. Harnessing compounding through regular investing plus time can transform modest contributions into significant wealth decades later. The first objectives include establishing healthy saving habits, avoiding high-interest revolving debt and learning fundamental investment concepts.
- Open a Roth IRA or employer retirement plan
- Choose broad, diversified, low-cost index funds
- Automate contributions to build discipline
- Keep a small cash buffer for emergencies
A starter emergency fund of one month’s expenses and low student-loan balances can coexist with aggressive stock exposure. Remember that a long horizon allows for higher volatility, but personal circumstances like income variability or imminent purchases may justify a more conservative tilt.
Stage 2: Early Career and Household Formation
As incomes rise and goals multiply, investors face competing objectives. By embracing goal-based investing and prioritization, you can allocate funds in accordance with each goal’s timeframe and risk profile. Your financial toolkit may now include multiple accounts and targeted savings vehicles.
Capturing the full employer match on a 401(k), expanding your emergency fund to cover family needs and managing student loans represent common priorities. Insurance, wills and other protections also become critical as dependents enter the picture.
Stage 3: Mid-Career Wealth Accumulation
By mid-career, your portfolio often spans taxable brokerage accounts, retirement plans and perhaps real estate. The main danger is drifting away from your intended asset mix or falling prey to sequence of returns risk as you approach large withdrawals later in life. Regular reviews can help maintain your target blend of stocks, bonds and cash.
- Rebalance at least annually
- Monitor concentration in employer stock
- Adjust risk after major life events
- Coordinate tax-benefited and taxable accounts
Beware of lifestyle inflation. Rising salaries often tempt higher spending, leaving little extra for investments. By pre-committing to increased savings rates or autopilot scheduling, you can channel growth into your long-term objectives.
Stage 4: Pre-Retirement Transition
As retirement nears, the emphasis shifts from accumulation to protection. Begin moving assets needed within the next five to seven years into less volatile vehicles. Build a cash-flow reserve to cover initial retirement expenses and reduce concentration risk. Evaluate Social Security claiming strategies, coordinate pension decisions and test withdrawal assumptions against projected expenses.
Tax planning gains urgency. Consider the interplay between taxable, tax-deferred and Roth accounts, and how different withdrawal sequences can affect your lifetime tax liability.
Stage 5: Retirement Income and Capital Preservation
In retirement, the name of the game is sustainable withdrawals. A common rule of thumb is a 3%–4% initial withdrawal rate, adjusted annually for inflation, but individual circumstances vary. Sequence of returns risk can erode a portfolio if markets underperform early. By holding a portion of reserves in cash or short-term bonds, you can avoid selling equities at market troughs and ride out volatility.
Incorporate annuities, pensions or guaranteed income streams as needed to cover essential expenses. Preserve legacy intentions through estate and tax strategies, ensuring your beneficiaries receive assets according to your wishes.
Investment Choices by Objective
Each goal may call for a different mix of asset classes. Growth objectives typically lean on equities, while income goals emphasize bonds and dividend-paying securities. Real estate, commodities and alternative investments can play roles in diversification, but require careful due diligence.
Remember that diversification can reduce—but not eliminate—risk. A balanced, low-cost portfolio aligned with your timeframe and tolerance often outperforms complex strategies that chase market timing or speculative gains.
Asset Allocation and Diversification
Your overall mix of stocks, bonds and cash should reflect both how much market turbulence you can endure and how soon you’ll need the money. Younger investors with longer horizons may tolerate higher allocations to equities, while near-retirees often shift toward fixed income. Periodic rebalancing enforces discipline and locks in gains from strong performers.
Maximizing Tax-Advantaged Accounts
Take full advantage of 401(k)s, IRAs, Roth options and 529 plans where appropriate. tax-advantaged retirement investment accounts can significantly boost long-term outcomes. Understand contribution limits, matching rules and income restrictions to avoid surprises and optimize efficiency.
Mind the Fees, Behavior, and Scams
High fees can erode returns over decades. Choose low-cost funds and be wary of fads promising quick riches. Maintain emotional resilience to avoid market-timing pitfalls, and verify credentials carefully before trusting any advisor. Staying informed is your best defense against fraudulent schemes and hidden cost structures.
Stage-by-Stage Checklist
Early stages: automate savings, avoid high-interest debt, start retirement accounts.
Mid-career: rebalance regularly, diversify globally, monitor tax strategies.
Pre-retirement: protect near-term assets, plan withdrawals, optimize Social Security timing.
Retirement: establish cash reserves, sequence withdrawals, preserve legacy plans.
By treating investing as a dynamic, life-stage process rather than a static allocation, you can align your portfolio with changing needs, reduce stress and increase the likelihood of reaching each financial summit.
References
- https://www.federalreserve.gov/publications/2026-economic-well-being-of-us-households-in-2025-savings-investments.htm
- https://www.investor.gov/introduction-investing/investing-basics/save-and-invest/learn-about-investment-options
- https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/investorgov-tips-2026-investor-bulletin
- https://www.sec.gov/featured-topics/saving-investing-teachers
- https://www.investor.gov/additional-resources/general-resources/publications-research/info-sheets/beginners-guide-asset
- https://www.congress.gov/crs-product/IF12928
- https://www.congress.gov/crs_external_products/IF/HTML/IF12928.web.html
- https://www.investor.gov/additional-resources/information/older-investors
- https://www.investor.gov/introduction-investing
- https://www.sec.gov/investor/pubs/tenthingstoconsider.htm
- https://www.investor.gov/
- https://www.federalreserve.gov/econres/scfindex.htm